Some links on this page may be promotional or referral-based. Overlooked Justice may earn compensation from qualifying actions at no additional cost to you. Offers and availability are subject to third-party terms. Editorial integrity remains independent.
The laws created to protect people, uphold neighborhoods, and preserve communities have become weapons in the hands of some homeowners’ associations and the rule of law.
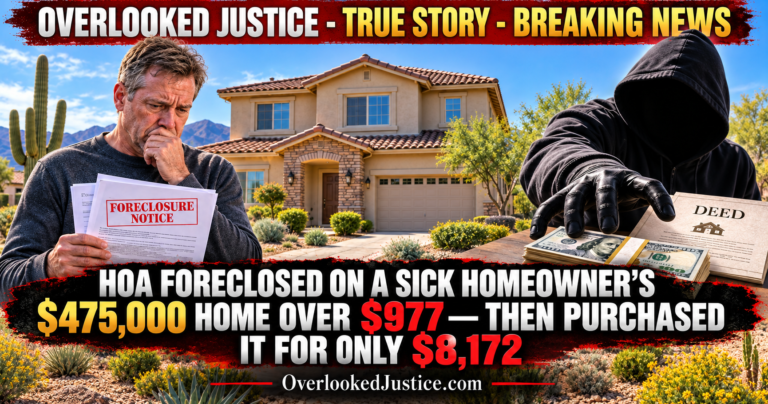
A 53-year-old Arizona homeowner fell behind by approximately $977 in HOA assessments after losing his job and being diagnosed with diabetes. What followed was not simply an attempt to collect a debt. It became a foreclosure that allowed the HOA itself to acquire his home—valued at approximately $475,000—for only $8,172.
A $977 Debt Led to the Loss of a $475,000 Home
Toby Newton purchased a four-bedroom home in Mesa, Arizona, in 2022. Records reviewed by news organizations place the original purchase price at approximately $449,328, while later reports describe the property as being worth approximately $475,000.
Newton reportedly planned to retire in the home with his longtime partner, Sherrie Patten.
In 2024, Newton lost his sales job and was diagnosed with diabetes. With his income interrupted and medical expenses growing, he fell behind on quarterly assessments owed to the Superstition Springs Community Master Association.
His original assessment debt reportedly totaled approximately $977.
Newton did not simply ignore the debt. According to published reports, he contacted the HOA and attempted to establish a payment arrangement. He initially offered to pay an additional $50 each month while remaining current on future assessments.
When that offer was rejected, Newton increased his proposed payments—eventually offering to pay $200 per month in addition to his regular HOA assessments.
Those proposals were also reportedly rejected.
The HOA Chose Foreclosure
On November 15, 2024, the Superstition Springs Community Master Association filed a judicial foreclosure complaint against Newton in Maricopa County Superior Court.
Court case:
Superstition Springs Community Master Association v. Newton
Case No. CV2024-032885
As the foreclosure process continued, the original $977 debt grew dramatically through assessments, collection expenses, attorney fees, and court costs.
Court filings reportedly listed:
- $1,311 in assessments, late charges, and related amounts
- $1,042.09 in collection and plaintiff costs
- $3,345 in attorney fees
- A total foreclosure judgment of approximately $6,579
A relatively small HOA debt had now become a legal judgment several times larger than the original amount.
On June 30, 2025, the court entered a default judgment authorizing the foreclosure sale.
The HOA Purchased the Home for Only $8,172
On October 16, 2025, the property was offered at a Maricopa County sheriff’s auction.
The winning bidder was not a family looking for a home. It was not an independent purchaser paying anything close to the property’s reported value.
The winning bidder was the Superstition Springs Community Master Association—the same HOA that initiated the foreclosure.
The HOA reportedly acquired Newton’s home using an $8,172 credit bid.
A property reportedly worth approximately $475,000 was taken through foreclosure over an original $977 assessment debt and purchased by the foreclosing HOA for only $8,172.
That purchase price represents less than 2% of the property’s reported value.
The same organization that claimed the debt, rejected the homeowner’s proposed payment arrangements, initiated the foreclosure, and benefited from the mounting legal expenses ultimately acquired the property.
This creates a direct and troubling conflict of interest.
Illness Struck the Household Again
While Newton was attempting to save his home, his longtime partner, Sherrie Patten, was diagnosed with breast cancer.
Patten underwent treatment and went on long-term disability. Her illness reportedly caused another major financial setback while the couple was attempting to raise enough money to recover the property.
The HOA reportedly provided a redemption opportunity, but the required amount eventually increased to approximately $10,484.
What began as $977 in unpaid assessments became a demand exceeding $10,000 as legal fees and additional expenses continued accumulating.
As of the latest published report, Newton and Patten remained inside the house while seeking legal relief and attempting to recover the property.
Arizona Changed Its Law—But Not in Time for Newton
When the HOA filed its case against Newton, Arizona law generally permitted an HOA to foreclose its assessment lien when a homeowner had remained delinquent for one year or owed at least $1,200 in assessments, depending on which threshold was reached first.
Arizona later strengthened its homeowner protections.
Under the current version of Arizona Revised Statute §33-1807, a planned-community HOA generally may not foreclose unless a homeowner:
- Has remained delinquent for at least 18 months, or
- Owes $10,000 or more in assessments, whichever occurs first.
The current law also directs HOA boards to make reasonable efforts to communicate with homeowners and offer reasonable payment plans before beginning foreclosure.
However, Newton’s foreclosure was filed before the revised protections took effect. The amended law did not automatically stop the proceeding already underway.
The law changed—but apparently too late to protect this sick homeowner and the equity he had invested in his home.
The current law also continues to permit HOA foreclosure once its statutory threshold is reached. The fundamental question therefore remains: Should a private HOA ever be allowed to take a family’s home and accumulated equity over an assessment debt?
This Was Not an Isolated Case
Newton’s case is not the only report of homeowners facing the loss of substantial property and equity over comparatively small HOA debts.
Similar cases across the country show how foreclosure laws can benefit associations, attorneys, collection companies, investors, and purchasers while homeowners lose properties worth hundreds of thousands of dollars.
Gil Gonzalez Ramos—Denver, Colorado
Gil Gonzalez Ramos said his family’s home of approximately 17 years was foreclosed on following nearly $5,000 in HOA fines involving grass, siding, and trash-can placement.
Ramos said he had remained current on his mortgage and did not understand that the Master Homeowners Association for Green Valley Ranch could pursue judicial foreclosure.
The property was reportedly sold to an investor, who then proposed renting the family’s former home back to them.
Despite the damage to the homeowner and the possibility of losing years of accumulated equity, no criminal charges against the HOA were reported.
Source:
https://www.the-sun.com/news/10857962/home-sold-not-missed-mortgage-payment-hoa-fines-colorado
Monica Villela—Denver, Colorado
Monica Villela, a divorced mother of four, said she discovered that her home had been sold when an investor appeared in her driveway with documents showing that he had purchased it at a foreclosure auction.
The foreclosure reportedly followed nearly $8,000 in HOA fines related primarily to weeds and garbage cans. The property was reportedly purchased for approximately $23,000.
A judge later determined that the investor’s purchase violated Denver’s affordable-housing restrictions. The ruling prevented the investor from continuing to control the property under that purchase.
However, that court ruling was not a criminal prosecution of the HOA. No criminal charges against the association were reported for initiating the foreclosure that placed the family’s home into the investor’s hands.
Source:
https://www.the-sun.com/news/14136571/hoa-foreclosure-auction-mom-battle-house-denver
Colorado Home Auctioned for Approximately $5,000—Then Listed for $420,000
Another Colorado homeowner reportedly lost a property after falling behind by approximately $4,889.31 in HOA assessments.
The home was auctioned in 2021 for approximately the amount of the HOA debt. Months later, the former homeowner reportedly saw the property listed for approximately $420,000.
The former owner described what happened as being robbed.
No criminal charges against the HOA were reported. Instead, lawmakers responded by proposing reforms intended to establish minimum auction prices, restrict legal fees, and provide former homeowners with additional time to recover their homes.
Source:
https://www.the-sun.com/news/11105489/hoa-colorado-foreclosed-bills-robbed
Cordell Lovett Sr.—Colorado
Cordell Lovett Sr. reportedly discovered that a home he had owned for approximately 20 years had been auctioned for only $11,773.
Lovett said he learned that the property was gone while preparing to sell it. He had planned to use the home’s accumulated equity for his retirement.
Notices were reportedly sent to the property where his son lived, but Lovett said he did not personally receive them.
No criminal charges against the HOA were reported.
Source:
https://www.the-sun.com/news/10961863/colorado-home-hoa-sold
Charlotte Home Nearly Sold for $4,400—North Carolina
A three-bedroom Charlotte home reportedly valued at approximately $335,300 was auctioned for only $4,400 after approximately $4,000 in HOA dues and legal expenses accumulated.
The auction reportedly lasted approximately five minutes.
The homeowner ultimately stopped the foreclosure by resolving the debt during North Carolina’s upset-bid period. Without that intervention, a home worth hundreds of thousands of dollars could have been lost for a few thousand dollars.
No criminal charges against the HOA were reported because the foreclosure proceeded through powers authorized under state law.
Source:
https://www.the-sun.com/news/11381076/home-sold-auction-hoa-foreclosure
Where Was the Accountability?
The Colorado Attorney General reportedly investigated the foreclosure practices involving the Master Homeowners Association for Green Valley Ranch but found no violation under the laws governing the association at that time.
No criminal charges were brought against the HOA for the reported foreclosures.
That does not mean the actions were fair, ethical, or free from conflicts of interest. It shows how conduct that appears predatory and self-interested can remain protected when lawmakers have already created a legal path for it.
When companies and associations can use their governing authority to foreclose on homes, generate thousands of dollars in legal expenses, and transfer valuable property for a fraction of its worth, who truly benefits?
The homeowner does not benefit.
The sick person does not benefit.
The family and community do not benefit.
The financial benefit goes to the organizations, attorneys, collection companies, investors, and purchasers positioned to use the system.
If the law allows those in authority to profit from the hardship they are responsible for enforcing, then the law itself deserves investigation.
Who Are These Laws Really Protecting?
HOAs were created to maintain communities, protect shared property, and preserve neighborhood standards. They were not created to become private governments capable of taking someone’s most valuable possession over relatively small debts.
When an HOA can reject payment proposals, add thousands of dollars in legal fees, foreclose on a sick homeowner, and then purchase the home itself for a fraction of its value, the system presents a serious conflict of interest.
The HOA becomes the debt collector, foreclosure initiator, beneficiary, and purchaser.
That is not community protection. It is a system capable of transferring a family’s home and accumulated equity to the same organization pursuing the debt.
The absence of criminal charges does not establish that these actions are morally right. It exposes a system in which what should be considered predatory conduct can be made legal by the people responsible for writing and enforcing the laws.
IAMV Perspective
The laws and governing by those that lead seem to prey on the citizens of this country instead of protecting us. Creating laws to validate their crimes and sins—overlooking their conflict of interest, even literally contributing to death.
As far as I’m concerned, when an HOA uses its authority to foreclose on a sick homeowner and then purchases that person’s home for pennies on the dollar, it should be criminal and that HOA should be removed from that community.
This appears predatory and self-interested. Who benefits when laws that are supposed to protect people and communities end up creating profit for the company or association in charge of governing that community?
No private association should be allowed to gain control of hundreds of thousands of dollars in homeowner equity over a comparatively small debt.
The laws governing HOAs across the United States must be changed immediately.
I believe the entire government on both sides needs a total rehaul. They are not protecting us. They are using their power to steal from us and kill us.
Homeowners need:
- Mandatory and affordable payment plans before foreclosure
- Independent judicial review of every proposed HOA foreclosure
- Additional protections for people experiencing illness, disability, unemployment, or financial hardship
- Limits on attorney fees and collection expenses
- Guaranteed protection and return of the homeowner’s remaining equity
- A prohibition preventing an HOA, its board members, attorneys, management companies, or related parties from purchasing a home they caused to be foreclosed
- Clear personal and criminal accountability when foreclosure authority is abused
A person’s home should never become a financial prize for an organization entrusted with protecting the community.
How many sick, elderly, disabled, unemployed, and financially vulnerable homeowners must lose everything before lawmakers act?
Watch the 12News Report
Supporting Sources
Original shared story:
Men’s Journal investigation:
Arizona Revised Statute §33-1807:
Additional national report:
The People’s Voice. Uncensored.